Your biggest clients are being pitched PMS and AIFs. Be the one they hear it from.
Portfolio Management Services and Alternative Investment Funds are where wealthy Indian families are putting their next crore. This page tells you plainly which distributors should step in, why it is worth it, what it takes, and how KiAlt helps you do it responsibly.
₹50 lakh
Minimum ticket for a PMS account
₹1 crore
Minimum commitment for an AIF
₹17.5 lakh Cr
AIF commitments, June 2026
2.2 lakh
PMS client accounts in all of India
A week you will recognise
Your client of twelve years sells a plot for ₹3 crore.
Monday
The bank sees the credit. A relationship manager calls before you even know about it.
Wednesday
He is shown a PMS with a famous name and a private credit AIF. Nobody asks about his goals.
Friday
He signs. A month later he asks whether he should move his mutual funds 'to keep everything in one place'.
You did not lose him on returns or service. You lost him because, on the one day it mattered, you had nothing to say about PMS and AIFs.
The market, in four numbers
Small in headcount, enormous in value
This is not a mass product. It is a few lakh families holding a very large share of India's investable wealth.
₹9.03 lakh Cr
PMS assets outside EPFO money
Wealth managed for individuals, families and corporates by 514 portfolio managers, as on 31 July 2026.
+23.6%
AIF commitments in one year
From June 2025 to June 2026, total commitments climbed to ₹17.53 lakh crore.
2.2 lakh
PMS accounts, nationwide
A small club. Each account starts at ₹50 lakh, so every single one matters to the distributor who owns the relationship.
~4 lakh
Accredited investors, if SEBI's proposal goes through
In August 2026 SEBI proposed a ₹5 crore securities-asset route to accreditation, which it estimates could widen the pool from about 1 lakh AIF investors today.
Sources: SEBI monthly report of portfolio managers (as on 31 July 2026); SEBI AIF data for the June 2026 quarter; APMI distributor registration norms; SEBI circular on AIF distribution commission (April 2023). Proposals marked as such are consultation papers and may change.
Know the products
PMS and AIF, explained the way you would explain them to a client
Portfolio Management Services
A SEBI-registered portfolio manager runs a portfolio in your client's own name. The shares sit in the client's demat account, so they can see every holding and every trade.
- Minimum ₹50 lakh per client
- Discretionary, non-discretionary or advisory
- Typically 15 to 30 stocks, far more concentrated than a mutual fund
Alternative Investment Funds
A privately pooled fund, registered with SEBI, that can go where mutual funds cannot: unlisted companies, private credit, real estate and hedge-style strategies.
- Minimum ₹1 crore per investor, unless accredited
- Money is committed first and drawn down in tranches
- Three categories, each with a different risk profile
Category I
Building the economy
Venture capital, SME, social impact and infrastructure funds. Long horizons, early-stage risk.
Distributor exam: NISM XIX-ACategory II
Private markets
Private equity, private credit and real estate funds. The largest category by far, roughly three-quarters of all commitments.
Distributor exam: NISM XIX-ACategory III
Listed-market strategies
Long-short, hedge and long-only equity funds that may use leverage and derivatives. The closest cousin to PMS.
Distributor exam: NISM XIX-BWhere each product sits
| Mutual Fund | SIF | PMS | AIF | |
|---|---|---|---|---|
| Minimum ticket | ₹100 to ₹500 | ₹10 lakh | ₹50 lakh | ₹1 crore |
| How it is held | Units of a pooled fund | Units of a pooled fund | Securities in the client's own demat | Units of a pooled, privately placed fund |
| What it can do | Diversified, tightly regulated | Long-short and tactical strategies | Concentrated, customised portfolios | Private equity, private credit, real estate, hedge strategies |
| Liquidity | Daily | Per scheme terms | Per agreement, usually open | Cat I and II closed-ended, three years or more |
| Who it suits | Everyone | Informed investors | HNIs wanting a tailored portfolio | HNIs and family offices with patient capital |
| Your certification | NISM V-A and ARN | ARN plus the NISM derivatives exam | NISM XXI-A and APRN | NISM XIX-A or XIX-B |
Which MFD should target this
This is not for every distributor. It may be for you.
An honest map of who should move now, who should prepare, and who should wait.
Established practices, ₹50 Cr and above
You already have families with ₹2 crore or more in mutual funds. They are the ones a private banker is calling this month.
Books with business owners
Promoters, traders, exporters and professionals with lumpy income: a business sale, a property deal, a bonus year. Large tickets arrive suddenly.
MFDs with NRI and returning-Indian clients
They compare you with global wealth managers and expect a shelf that goes beyond mutual funds.
Anyone who has lost a client to a wealth desk
If a client moved ₹1 crore to a bank RM 'for PMS', the next one will too. This is a defence line before it is a growth line.
Growing MFDs, ₹25 Cr to ₹50 Cr, with a few large families
You do not need fifty HNIs. Three or four families who trust you are enough to start. Get certified now, launch when they ask.
Wait, if any of these is true
- × Your ARN is new and the book is under ₹5 Cr. Build the mutual fund base first.
- × Almost all your clients are SIP investors below ₹25 lakh of investable wealth.
- × You are looking for quick upfront income. PMS and Category III AIFs pay trail only.
- × You would recommend these to a client who cannot afford to lock up or lose the money.
30-second readiness check
Tick what is true for your practice
0/6
Not yet, and that is fine.
Keep building the mutual fund book. Come back when a few families cross ₹50 lakh of investable wealth.
Why it is worth your time
Six reasons, none of them hype
One client, the weight of many
A single PMS account at the ₹50 lakh minimum brings in what roughly 17 SIPs of ₹5,000 contribute over five full years. One AIF commitment at ₹1 crore doubles that.
It is your best retention tool
HNIs rarely leave over returns. They leave because someone else offered a product you could not. A complete shelf keeps the whole family with you.
Trail income, the model you already know
PMS and Category III AIFs pay distributors on trail, never upfront. It rewards the long relationships you have spent years building.
Few distributors are equipped
APMI had issued just over 10,000 PMS distributor registrations by March 2025. The field is thin, and your HNI clients know very few people who can explain these products honestly.
The market is moving here
AIF commitments grew 23.6% in a year. Private credit, pre-IPO and long-short strategies are now dinner-table topics among wealthy families.
The regulator is widening the door
Accredited-investor-only AIFs are now part of the regulations, and SEBI has proposed easier accreditation and a lower-ticket MF-PMS format. More of your clients will qualify, not fewer.
What it takes
Five steps from ARN holder to PMS and AIF distributor
Exams and a registration, on top of the practice you already run.
01
Keep your ARN
Your mutual fund practice stays the core. PMS and AIF sit on top of it for the clients who qualify.
02
Clear NISM Series XXI-A
The PMS Distributors Certification. Valid for three years.
03
Get your APRN from APMI
Registration with the Association of Portfolio Managers in India has been mandatory for PMS distributors since 1 January 2025. The fee for individuals is ₹500 plus GST.
04
Add NISM XIX-A and XIX-B for AIFs
XIX-A covers Category I and II AIFs. XIX-B covers Category III. Take the one that matches what you plan to offer.
05
Empanel with managers
Sign distribution agreements with the portfolio managers and AIF managers whose strategies fit your clients.
How distributors are paid, by rule
PMS
Trail onlyNo upfront commission. Paid by the portfolio manager for as long as the client stays invested.
AIF Category III
Trail onlyEqual trail, paid out of the manager's management fee. No upfront fee, directly or indirectly.
AIF Category I and II
Up to one-third upfrontThe rest is paid as equal trail over the life of the fund.
Rates are set in your agreement with each manager. Every distribution fee must be disclosed to the investor.
Why KiAlt
The hard part is not the licence. It is knowing who, what and when.
Wealth desks have analysts, product teams and CRM systems behind every relationship manager. KiAlt gives an independent distributor the same backing, on the client data you already hold.
Interactive preview with sample data
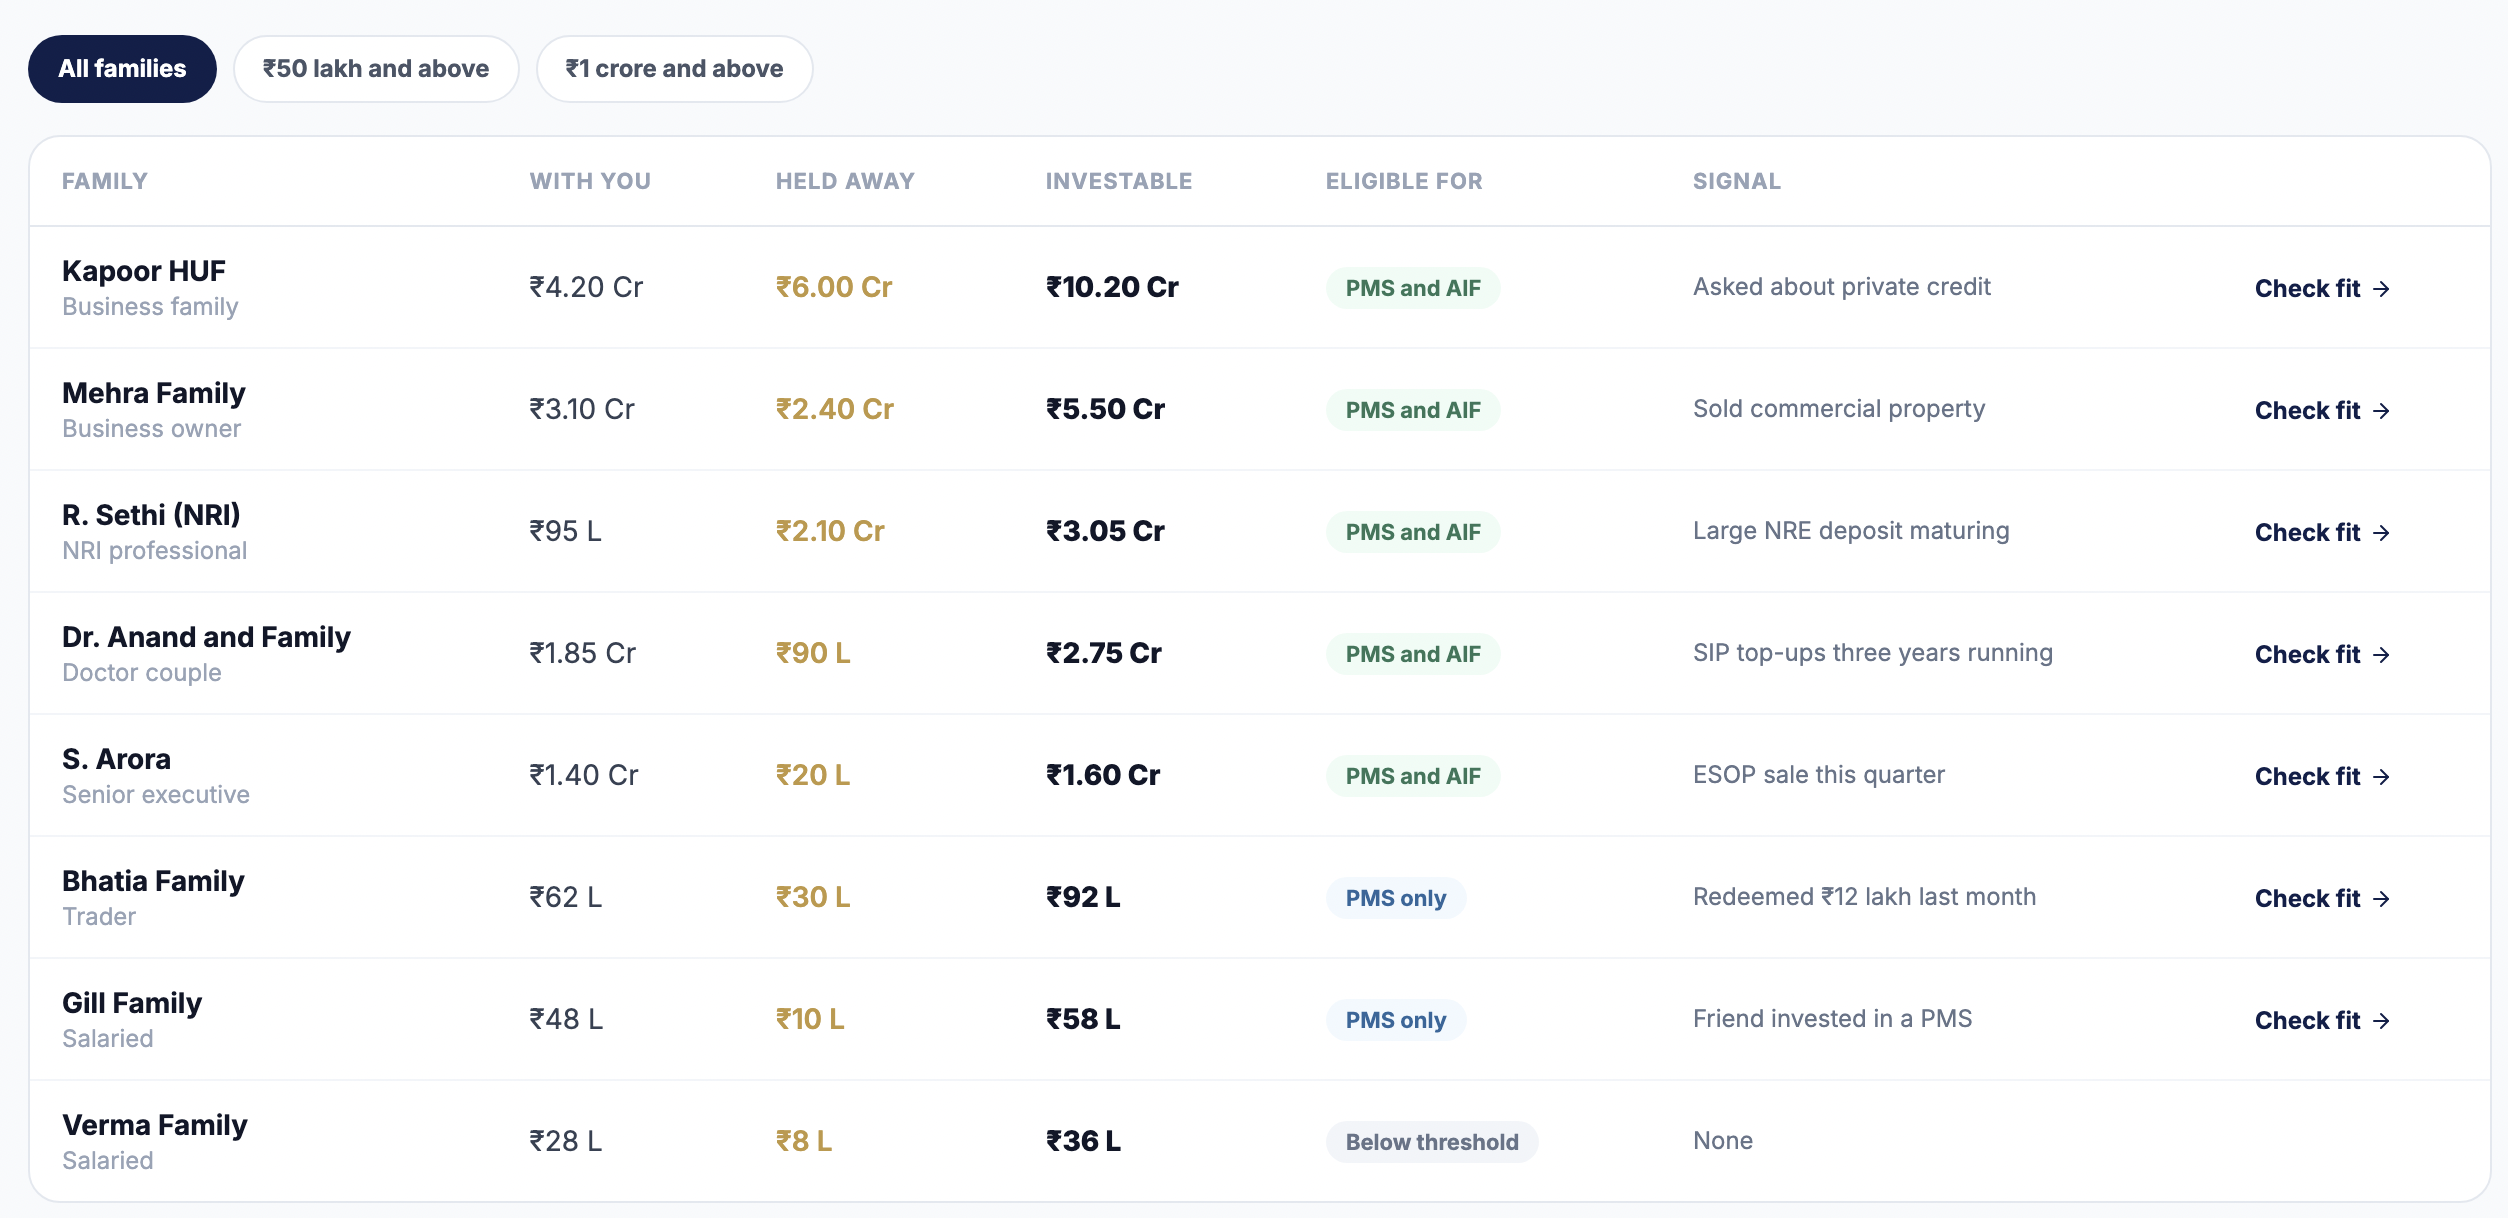
HNI Finder
Suitability check
HNI Finder
Scans your whole book and flags families who cross the ₹50 lakh and ₹1 crore lines, including assets held away that surface through KiScan and Wallet Share Finder.
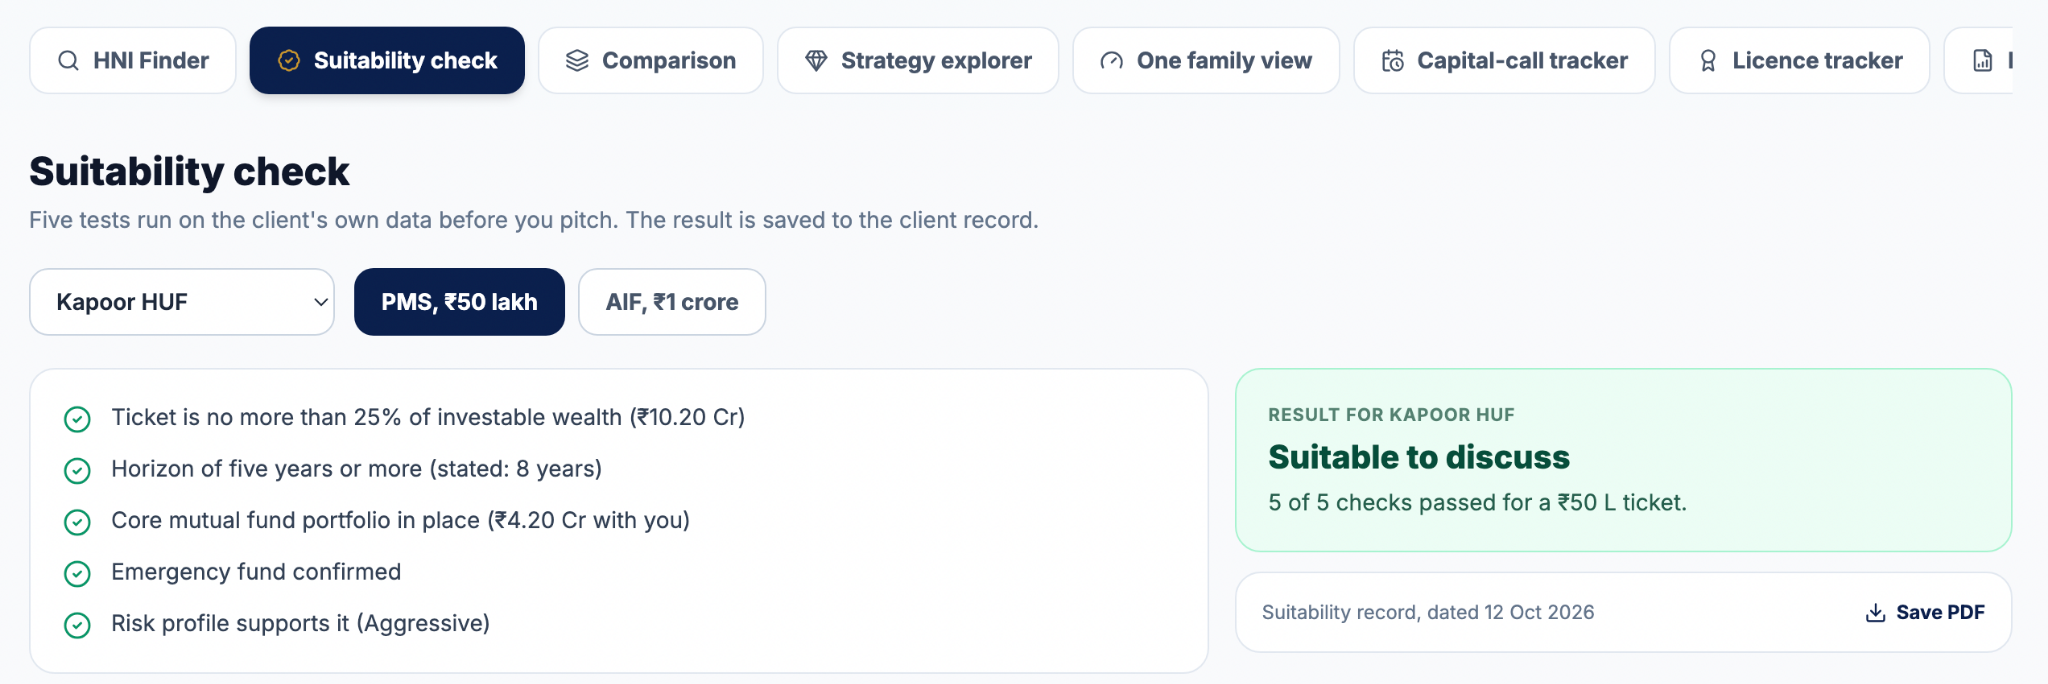
Suitability check
Risk profile, liquidity needs and concentration tested before you pitch, with a record you can show later.
MF vs SIF vs PMS vs AIF comparison
A clean, feature-by-feature view you can open in front of the client.
Open it nowStrategy explorer
PMS and AIF dossiers in the same format as your scheme dossiers: approach, manager, fees, track record, risk.
One family view
Mutual funds, PMS holdings and AIF commitments together inside Ki360, so the review meeting covers the full balance sheet.
Capital-call tracker
AIF drawdown notices, distributions and remaining commitments tracked per client, with reminders before each call.
Licence tracker
Your NISM XXI-A, XIX-A, XIX-B and APRN validity in one place, with renewal alerts well ahead of expiry.
Revenue Lens, by product line
PMS and AIF trail shown next to your mutual fund commission, so you can see the new line grow.
Pitch kit and Academy track
Client-ready explainers and a learning path that takes you from first exam to first allocation.
Independent
KiAlt does not manufacture or sell any PMS or AIF. The research has no product to push.
Built on your book
It starts from clients and data already inside your Cockpit, not from a cold list.
One login
Mutual funds, SIF, insurance, GIFT City and now PMS and AIF, in the same workspace.
Sell it right
The client conversation, before any product name comes up
The distributors who last in this segment are the ones who say no as often as yes.
A good fit when
- ✓ Investable surplus well above the minimum ticket, not just equal to it
- ✓ A horizon of five years or more for this slice of money
- ✓ An emergency fund and core mutual fund portfolio already in place
- ✓ Comfort with concentrated positions and uneven returns
Walk away when
- × The ticket is most of the client's liquid wealth
- × The money is needed for a known goal within three years
- × The client wants it mainly because a friend has one
- × The client has never sat through a sharp fall in a mutual fund
Regulatory watch
What has changed, and what is on the table
Last reviewed October 2026.
Accredited-investor-only AIFs
SEBI amended the AIF regulations to allow schemes meant only for accredited investors, who are exempt from the ₹1 crore minimum.
Mandatory APMI registration
PMS distributors must hold an APRN. No registration, no new clients and no commission.
₹5 crore asset route to accreditation
August 2026 consultation: individuals with ₹5 crore of securities-market assets could qualify as accredited investors.
MF-PMS at ₹25 lakh
SEBI's review of PMS regulations proposes a mutual-fund-based PMS format with a ₹25 lakh minimum, half the current ticket.
Questions distributors ask
Straight answers
No. Since 1 January 2025, anyone distributing PMS needs a valid NISM Series XXI-A certificate and an APRN from APMI. Your ARN continues to cover mutual funds.
Please note: KiAlt is a technology platform. It is not a portfolio manager, an AIF manager or a distributor, and nothing here is investment advice. PMS and AIFs carry higher risk and lower liquidity than mutual funds and are suitable only for investors who can bear losses. Features marked "Coming soon" are on our roadmap. The target profiles and AUM bands are KiAlt's view, not a regulatory requirement. Rules and figures are as of the dates shown; please confirm current requirements with SEBI, APMI and NISM before you act. Sources: SEBI monthly report of portfolio managers (as on 31 July 2026); SEBI AIF data for the June 2026 quarter; APMI distributor registration norms; SEBI circular on AIF distribution commission (April 2023). Proposals marked as such are consultation papers and may change.
The next ₹1 crore ticket in your book should come to you first
Tell us your AUM and how many large families you serve. We will show you what the PMS and AIF desk would surface in your book.